Buying a home is an exciting milestone, but if you’re concerned about your credit score, available savings, or income, you may be wondering whether homeownership is within reach.
The good news? You don’t necessarily need perfect credit or substantial savings to qualify for a home loan.
An FHA loan could help make homeownership possible, even if you’ve experienced some financial challenges along the way.
At Jet Direct Mortgage, we believe understanding your financing options is one of the most important steps toward becoming a homeowner. Let’s explore FHA loan requirements, who qualifies, and what you’ll need to get started.
What Is an FHA Loan?
An FHA loan is a mortgage insured by the Federal Housing Administration (FHA), a government agency within the U.S. Department of Housing and Urban Development (HUD).
Unlike conventional mortgages, FHA loans offer flexible financing opportunities for qualified borrowers, particularly those with limited savings or less-than-perfect credit.
Although the federal government insures these loans, FHA mortgages are issued by FHA-approved mortgage lenders, not directly by the government.
Some potential benefits of FHA financing include:
- Up to 96.5% financing for eligible borrowers
- More flexible credit score requirements than many conventional loan programs
- The ability to use eligible gift funds toward required borrower contributions
- Financing options for qualified first-time and repeat homebuyers
- Opportunities to purchase certain two- to four-unit properties when you plan to occupy one of the units
Interested in learning more? Explore FHA home loan options from Jet Direct Mortgage.
1. What Credit Score Do You Need for an FHA Loan?
One of the biggest advantages of FHA financing is its flexibility when it comes to credit scores.
Under FHA guidelines:
- Credit scores of 580 or higher: Eligible borrowers may qualify for up to 96.5% financing.
- Credit scores between 500 and 579: Eligible borrowers may qualify for up to 90% financing.
- Credit scores below 500: Borrowers generally do not meet FHA’s minimum credit score requirement.
However, there’s an important distinction between FHA guidelines and individual lender requirements.
Mortgage lenders may establish their own minimum credit score standards, sometimes called lender overlays, that are higher than FHA’s published minimums.
Your credit score also isn’t the only factor considered. Lenders review your overall financial situation, including your payment history, outstanding debts, income, and available assets.
Even if your credit isn’t where you’d like it to be, it’s worth exploring your options before assuming you won’t qualify.
Jet Direct Tip: A stronger credit profile may help you qualify for more favorable mortgage terms. If you’re unsure where you stand, speaking with a mortgage professional can help you understand your options and identify potential next steps.
2. How Much Financing Is Available With an FHA Loan?
One of the most common misconceptions about buying a home is that you need substantial savings before you can qualify for a mortgage.
FHA loans can help make homeownership more accessible by offering up to 96.5% financing for eligible borrowers.
The percentage of financing available generally depends on your credit profile and other qualifying factors.
For example, FHA guidelines may allow:
- Up to 96.5% financing for borrowers with qualifying credit scores of 580 or higher
- Up to 90% financing for eligible borrowers with credit scores between 500 and 579
These higher loan-to-value financing options may help qualified buyers preserve more of their savings for moving expenses, home improvements, or unexpected costs.
Can Gift Funds Help With FHA Loan Requirements?
Yes! FHA guidelines allow eligible borrowers to use properly documented gift funds from approved sources, including certain family members and other eligible donors.
These funds must meet FHA documentation requirements, and the gift generally cannot represent an undisclosed loan that you’re expected to repay.
Depending on your location and eligibility, you may also qualify for financial assistance through state or local homebuyer programs.
If you’re preparing to purchase your first home, visit our First-Time Homebuyer resources to learn more about getting started.
3. What Debt-to-Income Ratio Is Required for an FHA Loan?
Your debt-to-income ratio, commonly called DTI, is another important factor in determining whether you qualify for an FHA mortgage.
Your DTI compares your monthly debt obligations to your gross monthly income, or income before taxes.
Lenders generally consider two measurements:
Housing Expense Ratio
This measures how much of your monthly income would go toward your proposed housing payment, including principal, interest, property taxes, homeowners insurance, applicable mortgage insurance, and association dues.
Total Debt-to-Income Ratio
This includes your proposed housing payment plus other recurring monthly obligations, such as:
- Auto loans
- Student loans
- Credit card minimum payments
- Personal loans
- Other qualifying monthly debts
What Is the Maximum DTI for an FHA Loan?
For manually underwritten FHA loans, the standard qualifying ratios are generally 31% for housing expenses and 43% for total debt.
However, some borrowers may qualify with higher ratios based on their credit profile, available reserves, compensating factors, and the underwriting method used.
For example, certain manually underwritten loans may allow a total DTI as high as 50% when specific requirements are satisfied.
Automated underwriting can also produce different qualifying outcomes.
The takeaway: A higher DTI doesn’t automatically mean you can’t qualify. Your entire financial picture matters.
4. Are There Minimum Income Requirements for FHA Loans?
Here’s another encouraging feature of FHA financing: There is no universal minimum salary required to qualify for an FHA loan.
You don’t have to earn a specific annual income to be considered.
Instead, lenders evaluate whether your income is sufficient, stable, and likely to continue, based on applicable underwriting guidelines.
Your lender may review:
- Your employment and income history
- Current earnings
- Existing monthly debts
- Available savings and assets
- Other eligible sources of income
And you don’t necessarily need a traditional salaried job.
Depending on your circumstances, qualifying income may include self-employment earnings, retirement income, disability benefits, or other eligible documented income sources.
What If You’re Self-Employed?
Self-employed borrowers may also qualify for FHA financing, although documenting income can be more involved.
Lenders typically review tax returns and other financial records to determine qualifying income.
If you’re self-employed, working with an experienced mortgage lender can help you better understand which documentation may be required.
5. What Documents Do You Need to Apply for an FHA Loan?
Being prepared can help make the mortgage application process smoother.
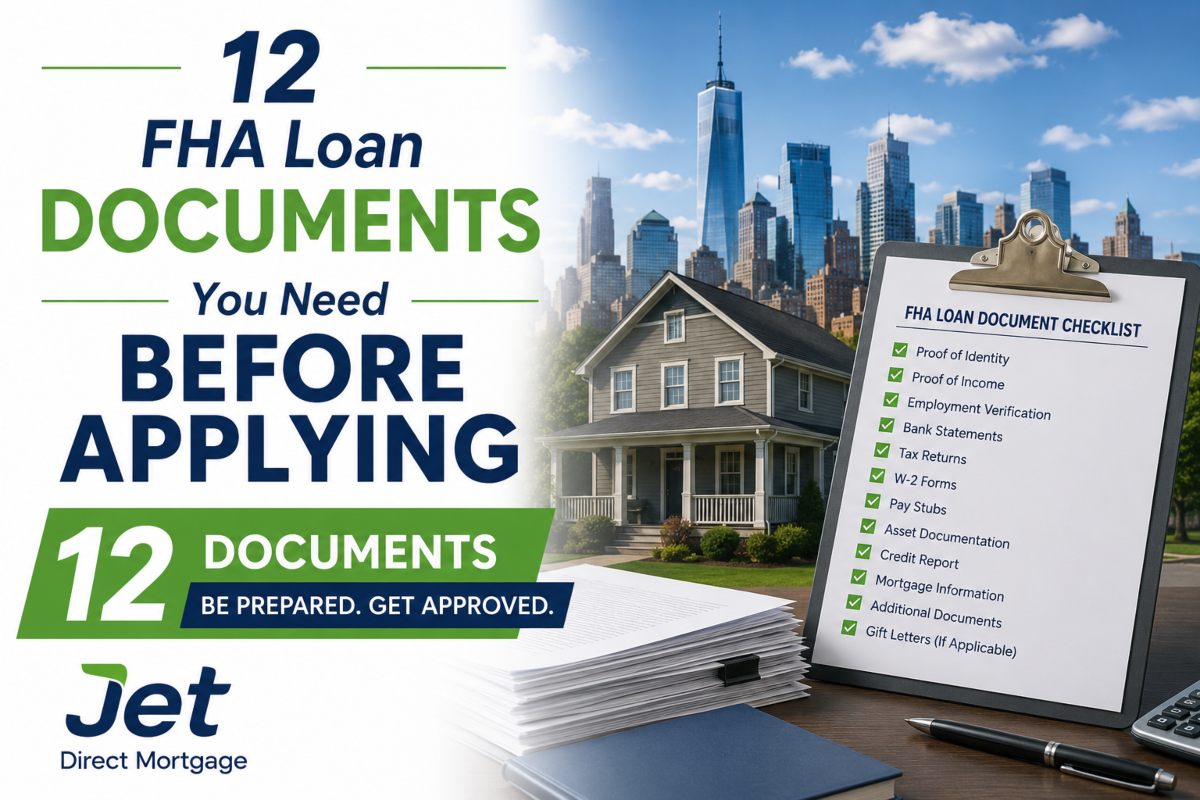
While documentation varies based on your employment, income, and financial circumstances, lenders commonly request:
- A valid government-issued photo ID
- Social Security number or other applicable identification documentation
- Recent pay stubs, if employed
- W-2 forms and/or tax returns, as applicable
- Recent bank statements
- Employment information
- Documentation of additional income sources
- Gift letters and supporting records, if using eligible gift funds
Self-employed applicants may need to provide additional business and financial documentation.
Not every borrower will need every document listed above. Your loan officer can help identify the information required for your particular situation.
Jet Direct Tip: Getting organized before you begin house hunting can help you prepare for mortgage preapproval and understand your purchasing power.
6. What Types of Homes Qualify for FHA Financing?
FHA loans aren’t just about borrower qualifications. The property you’re purchasing must also meet certain requirements.
In general, FHA financing is intended for a home that will serve as your primary residence.
Eligible property types may include:
- Single-family homes
- Certain condominiums that meet FHA requirements
- Two- to four-unit properties, provided you occupy one unit as your primary residence
- Eligible manufactured homes that meet applicable FHA property and foundation requirements
Typically, at least one borrower must establish occupancy within 60 days of signing the mortgage security instrument and intend to occupy the property for at least one year, subject to applicable exceptions.
Can You Buy an Investment Property With an FHA Loan?
FHA loans generally aren’t intended to finance vacation homes or properties purchased solely as investments.
However, purchasing a two- to four-unit property and living in one unit may be an option.
For example, you might purchase a duplex, occupy one unit, and rent out the other, provided you meet the applicable qualification and property requirements.
This approach can offer a path to homeownership while potentially generating rental income.
What About Fixer-Uppers?
FHA loans also have property condition requirements designed to address safety, security, and soundness.
A home that needs substantial repairs may not qualify for a standard FHA purchase mortgage in its current condition.
However, certain renovation financing programs, including the FHA 203(k), may allow qualified borrowers to finance eligible home improvements along with the purchase of a property.
Learn more about your options by exploring Jet Direct Mortgage’s home loan programs.
7. Do You Have to Be a First-Time Homebuyer to Qualify for an FHA Loan?
No! FHA loans aren’t just for first-time homebuyers.
Although FHA financing is popular among people purchasing their first homes, repeat buyers may qualify as well.
Whether you’ve owned a home before or are preparing for your very first purchase, FHA financing may be worth considering.
Keep in mind that FHA loans generally have primary-residence occupancy requirements, and borrowers typically cannot have more than one FHA-insured mortgage at a time unless they qualify for an exception.
First-time homebuyers may also have access to certain state and local assistance programs, depending on where they live and their individual qualifications.
If you’re just beginning your homeownership journey, our First-Time Homebuyer page is a great place to start.
8. Don’t Forget About FHA Mortgage Insurance
While FHA loans offer attractive financing options, it’s important to understand the costs associated with this type of mortgage.
FHA loans generally require mortgage insurance premiums (MIP), which help protect lenders against losses if borrowers default.
There are typically two components:
Upfront Mortgage Insurance Premium (UFMIP): Generally 1.75% of the base loan amount for most standard FHA purchase loans. This premium can often be financed into the mortgage.
Annual Mortgage Insurance Premium: Typically paid in monthly installments, with the amount depending on factors such as loan term, loan amount, and loan-to-value ratio.
Depending on your original loan-to-value ratio and loan terms, annual FHA mortgage insurance may be required for 11 years or for the life of the loan.
That’s why it’s important to compare the total costs of FHA financing with other available mortgage options, rather than focusing only on the percentage of financing available.
9. Is an FHA Loan Right for You?
An FHA loan can be an excellent financing option for qualified buyers, but it’s not necessarily the best choice for everyone.
You may want to consider FHA financing if:
- Your credit score makes conventional financing more challenging.
- You’re interested in financing options offering up to 96.5% of an eligible property’s value.
- You’re purchasing your first home.
- You want to explore financing for an eligible multiunit property you plan to occupy.
- You’re looking for a mortgage program with more flexible qualifying guidelines.
On the other hand, a conventional mortgage may offer advantages depending on your credit score, available assets, and overall financial situation.
The key is understanding your options before making a decision.
At Jet Direct Mortgage, our goal is to help you find financing that fits your needs—not simply put you into a one-size-fits-all mortgage.
Take the Next Step Toward Homeownership With Jet Direct Mortgage
Qualifying for a mortgage can feel complicated, especially when you’re navigating credit requirements, financing options, and lending guidelines for the first time.
But you don’t have to figure everything out on your own.
At Jet Direct Mortgage, our experienced mortgage professionals can help you explore FHA loan options, understand qualification requirements, and determine which financing solutions may be available to you.
Whether you’re buying your first home, returning to the housing market, or simply wondering if you qualify, we’re here to help you move forward with confidence.
Ready to find out if an FHA loan is right for you?
Contact Jet Direct Mortgage today to speak with a mortgage professional and take the next step toward homeownership.
All loans are subject to credit approval, underwriting requirements, program guidelines, and property eligibility. FHA guidelines and individual lender requirements may vary. Maximum financing percentages are based on applicable FHA loan-to-value requirements and do not necessarily include financed mortgage insurance premiums. Borrowers may be responsible for closing costs, prepaid expenses, and other applicable fees.

Megan Ringhoff is a licensed loan officer at Jet Direct Mortgage who prides herself in helping people change their lives for the better, helping them build wealth, and putting people and their families into a home with a backyard to call their own. Megan strives to find ways for her clients to get the best possible deal to fit their situation and will do anything to make their dreams come to reality. NMLS#2040719