Think your credit score puts homeownership out of reach? Before you put your plans on hold, it’s worth getting the full picture.
The way mortgage lenders evaluate credit is evolving. New scoring options and updated underwriting requirements mean that advice you heard a few years ago may no longer tell the whole story.
Whether you’re buying your first home or preparing for your next move, here are three things Jet Direct Mortgage wants you to know.
1. There’s No Universal Credit Score Requirement
You may have heard that you need a credit score of at least 620 to qualify for a mortgage. But that number doesn’t apply to every loan or every borrower.
Fannie Mae has removed the minimum third-party credit score requirement for loans evaluated through Desktop Underwriter, its automated underwriting system. Instead, the system evaluates the borrower’s broader credit profile and other risk factors. Minimum scores still apply to certain other loans, and lenders may have additional requirements.
This doesn’t mean credit scores no longer matter—or that approval is automatic. Your income, debts, savings, payment history, and loan program requirements all help determine your eligibility.
Different mortgage programs also offer different paths to homeownership. Exploring options such as conventional home loans and FHA home loans with a loan officer can help you understand which programs may fit your circumstances.
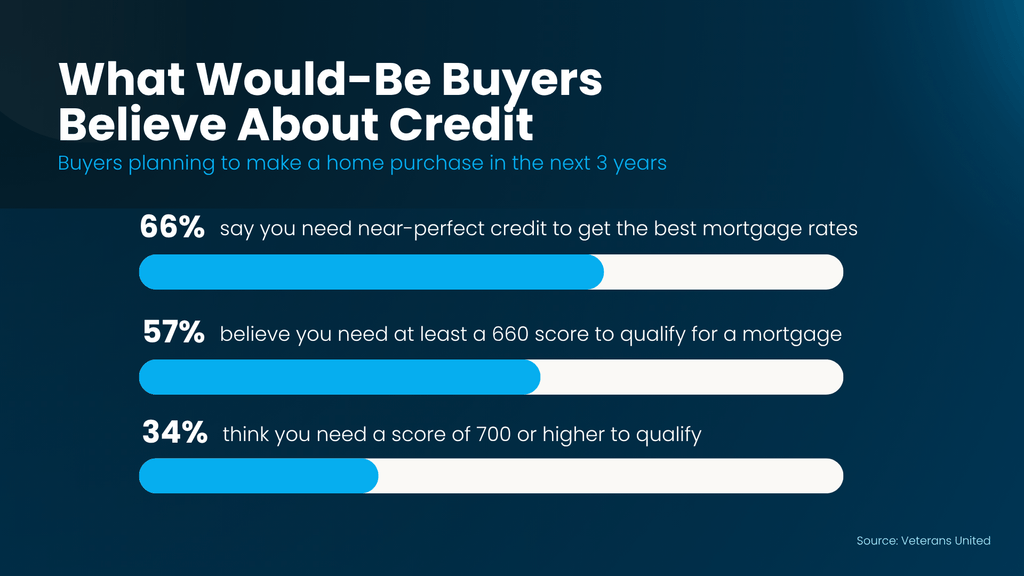
The takeaway: Don’t rule yourself out based on a number you heard from a friend or found online. Find out what applies to your situation.
2. Your Credit App May Not Show Your Mortgage Score
Checking your credit through an app is a useful habit. But the number you see may differ from the score used for your mortgage application. Different scoring models can produce different results—even when they evaluate the same person.
For years, Classic FICO was the standard for mortgages sold to Fannie Mae and Freddie Mac. Lenders can now choose VantageScore 4.0 for eligible loans. Another approved model, FICO 10T, is still awaiting implementation for loans delivered to those agencies. Which model is available depends on the lender and loan program.
These changes are intended to modernize credit evaluation. They don’t guarantee a higher score, a lower interest rate, or mortgage approval.
The takeaway: Treat the score in your app as a starting point. Your loan officer can explain which score is used for your application and how it affects your options.
3. Strong Credit Habits Still Make a Difference
Scoring models may change, but the habits that support healthy credit remain familiar:
- Pay bills on time. A consistent payment history is a major factor in building strong credit.
- Keep credit card balances low. Using less of your available credit can help your credit profile.
- Limit unnecessary credit applications. Be especially thoughtful about opening new accounts as you prepare to apply for a mortgage.
- Review your credit reports. Look for unfamiliar accounts, incorrect balances, or other errors that need attention.
- Discuss major changes with your loan officer. Before closing accounts or making substantial credit decisions, ask how those steps could affect your mortgage application.
Preparing to buy also means understanding what fits comfortably into your budget. Our mortgage calculators can help you explore estimated payments as you plan. Your actual payment and loan terms will depend on your individual circumstances.
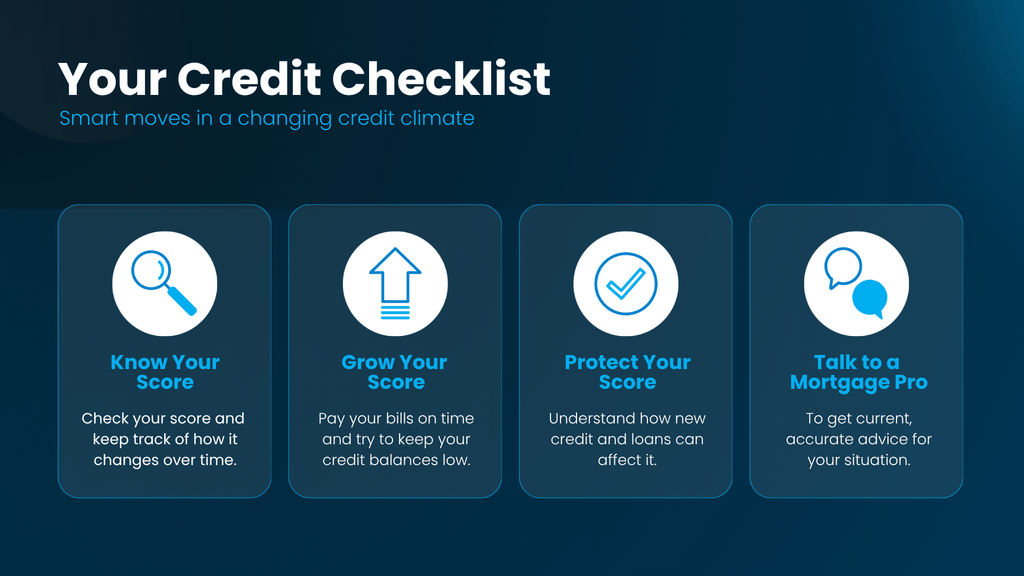
The takeaway: Focus on consistent habits and a realistic budget. Both can help you prepare for your next step.
Find Out Where You Stand
You don’t need to master every credit scoring change before starting a conversation about homeownership.
At Jet Direct Mortgage, our loan officers can review your financial picture, explain available mortgage programs, and help you identify practical next steps. You may be ready to move forward, or you may benefit from a plan to strengthen your finances first. Either way, knowing your options is more useful than guessing.
Contact Jet Direct Mortgage to explore your home financing options and take your next step with confidence.
All loans are subject to credit and underwriting approval. Eligibility requirements vary by loan program and lender.
Source: Keeping Current Matters

Experienced Chief Operating Officer with a 26 + year demonstrated history of working in the banking industry. Skilled in all aspects of the residential mortgage market . Strong business development professional with a Bachelor of Science (BS) focused in Business Administration and Management, from St. Joseph College. A direct endorsement underwriter and a licensed Mortgage Loan Originator.